 Facebook
 X
 Pinterest
 Copy Link
Is Now a Good Time to Buy or Sell Real Estate?
Why the Right Time Depends on More Than Just the Market
It’s one of the most common questions in real estate: Should I buy or sell now, or would I be better off waiting?
With mortgage rates remaining elevated, home prices holding steady, and inventory levels shifting, it’s understandable why both buyers and sellers might feel uncertain about their next move.
The truth is, there isn’t a one-size-fits-all answer. While national headlines provide a snapshot of the housing market, real estate is local—and your personal circumstances matter just as much as market conditions.
Let’s take a closer look at what buyers and sellers should consider before making their next move.
Recent market estimates paint an interesting picture:
- Mortgage Rates: With 30-year fixed mortgage rates hovering around 7%–7.5%, affordability continues to be a challenge for many buyers.
- Home Prices: The national median home sale price remains high, with recent estimates around $393,000–$394,000.
- Inventory: More homes are becoming available nationally, giving buyers additional choices and, in some markets, greater negotiating power.
However, not every region is experiencing the same conditions.
Some parts of the country are shifting toward a buyer’s market, but here in the Midwest many communities continue to experience limited inventory and healthy buyer demand.
That’s why understanding your local market is so important.
Thinking About Buying? Here’s What You Should Know.
If you’ve been waiting for the perfect moment to purchase a home, you may be waiting longer than necessary.
Rather than trying to time the market, focus on whether buying makes sense for your financial situation and long-term goals.
- Buy When You’re Financially Ready
Having manageable debt, an emergency fund, a comfortable down payment, and a monthly housing budget you can realistically afford are far more important than trying to predict where mortgage rates will go next.
Remember, if rates decrease in the future, refinancing may be an option. However, refinancing is never guaranteed, so make sure you’re comfortable with today’s payment before purchasing.
- Don’t Be Afraid to Negotiate
In markets where inventory is increasing and homes are taking longer to sell, buyers may have opportunities to negotiate purchase prices, request repairs, or ask sellers to contribute toward closing costs.
Even in competitive markets, having an experienced real estate professional who understands local conditions can make a significant difference.
- Remember That Real Estate Is Local
National housing trends don’t necessarily reflect what’s happening in your neighborhood, so don’t depend on the national news reports.
For example, buyers in certain Sun Belt markets may find more inventory and negotiating opportunities, while buyers here in the Chicagoland area may still encounter multiple-offer situations on desirable, well-priced homes.
Knowing what is happening in the communities you’re considering will help you make a smarter purchase. That’s why you want to work with a local real estate agent, like me.
Thinking About Selling? Here Are Three Things to Consider.
If you’re a homeowner contemplating a move, today’s market presents its own set of opportunities and challenges.
- Consider Your Current Mortgage Rate
Many homeowners secured mortgage rates around 3% or 4% in previous years. Understandably, giving up that rate to purchase another home at today’s higher rates can be a difficult decision.
Before listing, it’s important to understand what your next home will cost—not just the purchase price, but your anticipated monthly payment.
- Know How Much Equity You Have
Homeowners who have owned their properties for several years may have built substantial equity.
Before selling, review your estimated market value, remaining mortgage balance, and anticipated selling expenses. Depending on your circumstances, total selling costs may reach approximately 8%–10% of the sale price.
Understanding your potential net proceeds will help determine how much purchasing power you’ll have for your next home.
- Price It Right From the Beginning
Today’s buyers are informed, selective, and increasingly conscious of affordability.
While properly priced homes in desirable locations can still attract strong interest, overpricing may cause a property to sit on the market longer than necessary.
A thoughtful pricing strategy, professional presentation, and effective marketing are essential to attracting serious buyers.
And remember, selling a home isn’t always about chasing the highest possible price. Sometimes it’s about moving closer to family, downsizing, relocating for work, or finding a home that better suits your lifestyle.
Those reasons don’t necessarily need to wait for the perfect market.
So, Should You Buy or Sell Now?
Here’s my perspective: The right time to make a move is when the move makes sense for YOU.
Trying to perfectly time the real estate market is nearly impossible. Interest rates fluctuate, inventory changes, and home prices respond to local supply and demand.
What matters most is having a clear understanding of your goals, your financial position, and the opportunities available in your specific market.
Whether you’re a first-time buyer, considering a move-up purchase, thinking about right-sizing, or simply curious about your home’s current value, having accurate information is the best place to start.
Let’s Talk About Your Next Move!
You don’t have to navigate today’s changing real estate market alone.
If you’re wondering whether now is the right time to buy or sell, I’d be happy to help you explore your options, evaluate current market conditions, and create a plan that works for your situation.
Because in real estate, the best decisions aren’t made by following headlines. They’re made by understanding your options.
Let’s connect and talk about what makes sense for you. Don’t forget to request copies of my Seller’s Guide, Buyer’s Guide and Senior’s Guide!
Karen Daugerdas, Coldwell Banker REALTOR®, Pricing Strategy Advisor®, Seniors Real Estate Specialist, Short sale Foreclosure Resource®, Accredited Buyers Representative®.
Moving In Day: First Steps
Buying a home is an exciting time, but it’s important to make every minute count when moving into your new space. Use this checklist to streamline the moving process so you can truly enjoy the excitement that comes from such a life-changing purchase.
The first twenty-four hours in your new home is crucial, but it doesn’t have to be stressful. Here’s what you can do to make the move count.
Prior to moving, make sure to pack one box with all the necessities you need for the first day and night in your new home. You don’t want to be rifling through boxes looking for a fresh towel, toilet paper, pajamas, blankets & pillows. Don’t forget the dog food and water bowl. Pack whatever you deem essential in a box, and label appropriately.
Double-check all rooms for any issues right away. A thorough inspection of the house will bring any problems to light—which makes fixing these problems easier to take care of before furniture is unloaded and items are hung up!
Wipe down all countertops and frequently used areas. Cleaning should be a no-brainer when getting settled in a new space, but with all of the chaos that moving in entails, it can easily get overlooked. Remember to break out the broom, cleaning spray, and paper towels to freshen up main areas.
Try to unpack one box in each main room. While you can’t do it all at once, having at least one box cleared per room will make it easier when you go to do the rest of the unboxing.
Lastly, start researching local doctors and dentists, as well as any other essential numbers to have—like babysitters in the area and the best pizzeria. You don’t want to be scrambling at the last minute if someone gets sick or you simply need a quick slice for dinner.
Follow the guide below for additional tips!
Day 1: Safety & Essential Systems
• Change the locks: Replace or rekey all exterior door locks, reset your garage door openers, and update smart-lock or keypad codes so previous owners or contractors no longer have access.
• Locate shut-off valves: Find and test the main water shut-off valve, gas shut-off valve, and electrical circuit breaker panel. Label individual circuit breakers for quick reference.
• Test safety devices: Test all smoke detectors and carbon monoxide detectors, replace expired units (detectors typically last 7 to 10 years), and place fire extinguishers in the kitchen and garage.
• Confirm utilities: Ensure electricity, gas, water, trash removal, and internet services are active and transferred to your name.
• Week 1: Clean & Inspect
• Deep clean surfaces: Sanitize empty kitchen cabinets, drawers, bathrooms, and windows before filling them with your belongings.
• Replace filters: Change the HVAC air filter and the refrigerator water filter.
• Inspect the exterior: Check gutters, downspouts, and window wells to make sure water flows away from the foundation.
• Update your address: Submit a change-of-address form with the USPS, and update your address with your bank, employer, insurance company, and utility providers.
Moving into a new home is an exciting time, so make the most of it! Karen Daugerdas, Coldwell Banker Realty, karen.daugerdas@cbrealty.com.
Why and How Condo Lending Rules Are Changing
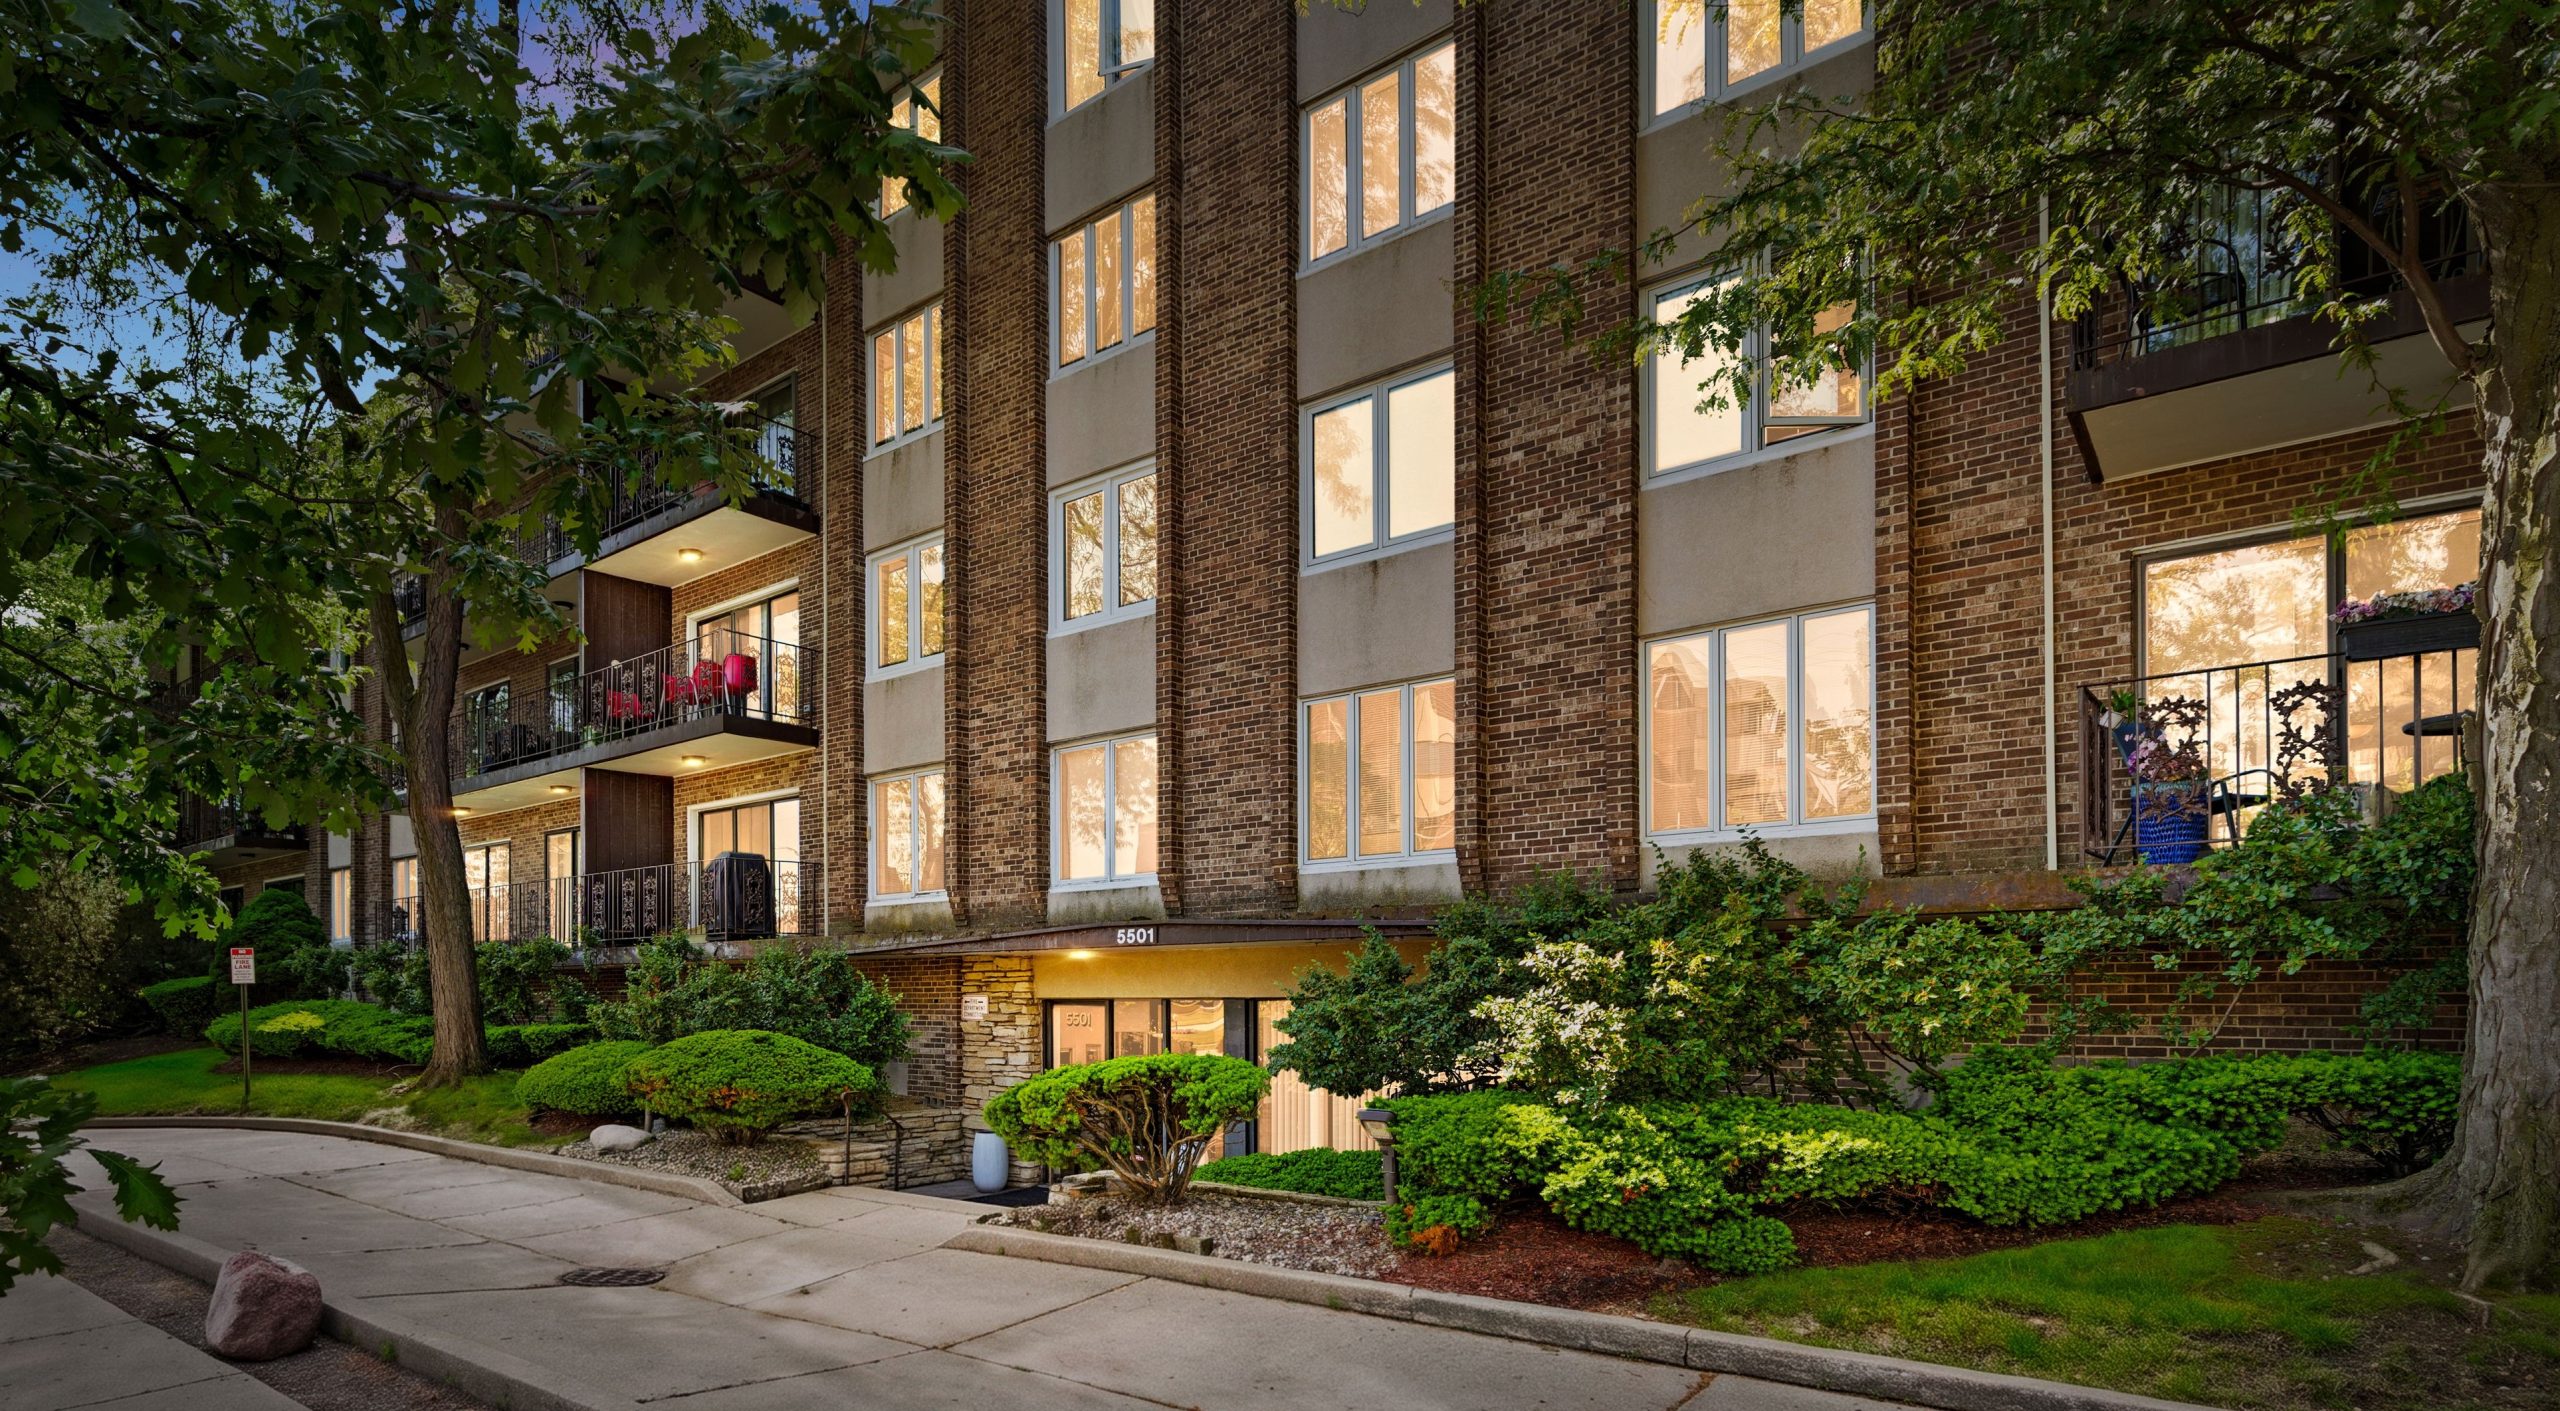
According to the National Association of REALTORS®, Fannie Mae and Freddie Mac have eliminated limited reviews for condominium financing, raising concerns about transaction delays, but other rule changes—such as a waiver for smaller buildings and elimination of a maximum percentage of investor-owned units—should ease underwriting. Still, a new, higher reserve requirement for homeowners associations raises affordability concerns.
Fannie Mae and Freddie Mac help finance nearly half of all home purchases, so when they change their rules, it can have a significant impact on the market. Recent changes to their policies for financing condominium mortgages will help some consumers but pose challenges to others.
Impact of Surfside Collapse
It helps to look back a few years at how Fannie Mae and Freddie Mac—also referred to as the government sponsored enterprises or GSEs—responded to the 2021 collapse of a building in Surfside, Fla., which killed 98 people.
Investigations revealed that the building needed major repairs but lacked the reserves to pay for them. At that time, the GSEs implemented new rules mandating engineering and structural studies as well as financial studies and disclosures. Lenders must verify that these studies and disclosures are in place, and collect information on needed or planned repairs, among other things.
Those rule changes enabled borrowers with down payments of 25% or more or other positive factors to use a limited review process with fewer hurdles and less documentation required. Otherwise, lenders were responsible for a full review that included collecting all documents and verifying the GSEs’ requirements. The 2021 rules were aimed at improving safety but also making HOAs more financially stable.
The New Rules
The changes made this spring implement lessons learned from several years with the post-Surfside rules. Rules that made sense in 2021 but didn’t improve safety are being relaxed, while other rules are being tightened. Specifically, the limited review, which allowed lenders to skip some documentation and checks, was eliminated. However, the GSEs will allow HOAs with 10 or fewer units a waiver from a full review, reducing the burden on small projects.
In addition, the GSEs eliminated the stipulation that no more than 50% of units in a project could be investor-owned, which should help improve demand and value. However, this change could create additional competition for owner occupants.
Although limited reviews are gone, Fannie Mae provides an option that may help HOAs manage this change. Fannie Mae’s Condominium Project Manager is a database of all condominium projects that meet Fannie Mae’s standards. This service, new in 2023, eliminates the need for lenders to submit full reviews once Fannie Mae has approved a project. Thus, once one lender submits documentation and the project is approved, all approved lenders can see the project’s status and no review is needed for subsequent transactions, eliminating costly and redundant fees for documents and questionnaires. HOAs can look up their status on Fannie Mae’s website and work with an approved lender to submit documentation for approval. Unfortunately, REALTORS® do not have access to this database unless they are an HOA’s official representative, nor can they submit documentation for approval. NAR believes this should change as REALTORS® are engaged far earlier in the process.
Higher HOA Reserve Requirement Raises Concern
However, some changes raise concerns. The GSEs raised the reserve requirement for HOAs from 10% to 15%. Alternatively, the GSEs will allow HOAs to use a reserve study to determine the appropriate amount of funds, but the HOA must use the highest estimate from the study. The 50% increase in reserves is problematic, and the timing of the GSEs’ mandate exacerbates the issue, creating a short timeframe for HOAs to transition to higher reserves. This problem will have a particularly acute effect on low- and moderate-income condo owners; those on fixed incomes like retirees; and regions facing other financial stresses like rising insurance rates and taxes.
National Association of REALTORS® leaders have expressed concern about the larger reserves and short time for the transition. It could pose significant affordability challenges to both existing homeowners and prospective home buyers, stifling an important part of the trade-up and trade-down market. NAR has shared these concerns with the GSEs and will continue to work with them to ameliorate the impact, while sharing information about the changes with REALTORS®.
Information courtesy of Ken Fears, director of conventional housing finance and valuation policy for the National Association of REALTORS®.
If you have real estate questions, contact Karen Daugerdas, Coldwell Banker Real Estate Broker, 847.494.1102.
Cook County: Prepare for Your 2025 Second-Installment Property Tax Bill to be Delayed
If you’re a Cook County homeowner, here’s something important on your radar: the 2025 second-installment property tax bill, normally mailed in July and due in August, is delayed. There’s no firm new date yet, but expect at least a one-month delay, possibly two or more.
This isn’t the first delay, either. The first installment was already pushed from February to March 2026, so we’re seeing a compounding pattern.
Here’s what matters most right now:
✅ Check your exemptions. Homeowner and senior exemptions appear on the second installment, not the first. Use your PIN on the Cook County Treasurer’s Office portal to scan for missing exemptions, uncashed refund checks, or overpayments going back up to four years.
✅ Know your options if something’s wrong. If your bill arrives with a missing exemption, don’t just pay it. You may be able to file a Certificate of Error through the Cook County Assessor’s portal to get an adjusted bill or a refund.
✅ Track your reassessment timeline. Visit the Cook County Assessor’s Interactive Map and enter your PIN or address to view your property profile and when your parcel is scheduled for reassessment.
✅ Budget ahead with the Rule of 12s. Set aside 1/12 of your estimated annual property tax each month, in a separate account or a mental “cookie jar.” Lenders do this with escrow accounts, and it’s a smart way for homeowners to stay ahead of delayed or lump-sum bills.
✅ Stay informed. Sign up for alerts at the Cook County Treasurer’s Office portal and check your property status regularly at the Cook County Property Tax Portal.
Delays like this can disrupt budgeting for both homeowners and the taxing agencies that depend on timely revenue, so the more prepared you are, the better.
Questions about how property taxes affect your buying, selling, or financial planning decisions? I’m always happy to help.
📞 847-494-1102
📧 karen.daugerdas@cbrealty.com
Karen Daugerdas, Your Family REALTOR®, Coldwell Banker Realty Serving the Chicago North Shore
Which home improvements increase value the most?
Which home improvements increase value the most? Short answer: curb appeal projects first, then targeted kitchen updates and bathrooms.
Why that order? Buyers form an opinion in seconds. Exterior upgrades create immediate visual impact for a fraction of the cost of a full interior remodel. Inside, buyers pay for clean, functional, updated spaces, not custom or over-the-top finishes. Below is a practical, numbers-driven guide based on the Remodeling Magazine / Zonda 2025 Cost vs. Value Report (national averages; outcomes vary by market).
Top categories to focus on before selling
- Curb appeal: garage door, front entry, exterior cladding
- Kitchen: minor remodel only; skip the gut renovation
- Bathrooms: mid-range remodel or a bathroom addition
Headline numbers from the 2025 Cost vs. Value Report (These are national averages; your local market will change the math.)
Highest-return projects (examples)
- Garage door replacement: 268% ROI. Avg cost: $4,672. Avg resale value added: $12,526.
- Steel entry door replacement: 216% ROI. Avg cost: $2,435. Avg resale value added: $5,270.
- Manufactured stone veneer (lower front facade): 208% ROI. Cost ≈ $11,000. Resale value added ≈ $22,880.
- Fiber-cement siding (full replacement): 114% ROI. Cost ≈ $19,000+.
Why curb appeal wins Buyers form emotional reactions in the first 15 seconds. Visible, appropriately styled upgrades (garage door, front door, stone veneer, paint, landscaping) punch well above their cost. Many of the top-performing projects are relatively affordable but transform perceived value immediately.
Kitchen improvements: add value, but only up to a point.
- Minor kitchen remodel: 113% ROI. National avg cost: $28,458. Resale value added: $32,141. This typically includes replacing cabinet doors/drawer fronts (keep boxes), new counters, sink/faucet, new mid-grade appliances, and updated flooring.
- Major/upscale kitchen remodel: ~52% ROI. High-end custom cabinetry, commercial appliances, luxury finishes — expensive and rarely recouped in typical markets.
- What doesn’t add value in many markets:
- High-end custom cabinetry in a mid-priced neighborhood
- Commercial-grade appliances in a starter home
- Moving plumbing/gas lines for layout changes
- Highly personalized designer finishes Rule of thumb: match the kitchen’s finish level to the neighborhood comps. Minor, functional updates usually beat a full gut when you’re selling.
Bathroom improvements: scope matters
- Bathroom addition (e.g., adding a half bath): Adds roughly $13,000–$26,000 in resale value. Cost: $15,000–$30,000 for a basic addition. Highest absolute value when a home is under-bathed for its bedroom count.
- Midrange bath remodel: 80% ROI. Avg cost: $26,138. Resale added: $20,910. A strong, consistent performer.
- Universal design remodel (walk-in shower, grab bars, wider doors): 61% ROI. Growing in appeal as buyers age.
- Upscale bath remodel: 42% ROI. Luxury finishes have limited resale power in non-luxury markets.
Curb appeal specifics that consistently perform
- Garage door replacement: 268% ROI (see numbers above)
- Steel entry door: 216% ROI
- Manufactured stone veneer: 208% ROI
- Fiber-cement siding: 114% ROI
- Landscaping and exterior paint: not separately tracked in Cost vs. Value but regularly cited by agents as top pre-sale investments. A professional paint job ($3k–$5k) and tidy landscaping can dramatically improve first impressions.
Improvements that typically don’t pay off
- Swimming pools: Installation $40k–$100k+. Appraisers usually add only $5k–$15k in many markets; may reduce buyer pool. Exceptions: luxury homes or warm-weather markets where pools are expected.
- Over-improving beyond the “comp ceiling”: Luxury upgrades in average neighborhoods rarely get dollar-for-dollar back.
- Large sunroom/additions: $75k+ cost, often 30–50% return depending on market.
- Highly personalized items (wine cellars, home theaters, bold custom work): value to the owner, not to most buyers.
Solar panels: a special note
- Solar generally increases home value by about 4%–7% nationally (roughly $10k–$18k for a median-priced home).
- Ownership matters:
- Owned systems: treated as an owned asset and can boost appraisal value, especially in high-cost markets (5%–10% increase in places like California).
- Leased systems / PPAs: typically do not add equity. Buyers may need to assume the lease, which can deter offers. Consider how your system is financed before assuming solar will raise your sale price.
Prioritize improvements before you list. Start with what buyers see first and what buyers worry about:
- Curb appeal (garage door, front door, landscaping, exterior paint): do this first. Highest ROI and first-impression impact.
- Kitchen: do a minor remodel if the kitchen is functionally dated. Replace worn cabinet doors, counters, and appliances that clearly need it.
- Bathrooms: repair failing grout/caulk and leaky fixtures; if remodeling, keep it mid-range. Consider adding a half bath if the home is under-bathed.
- Deferred maintenance: failing HVAC, roof near end-of-life, water intrusion: fix these. These are minimums buyers expect; inspectors will flag them and buyers will discount for them.
- Skip pools, major additions, and highly personalized upgrades unless you’re in a market that specifically values them.
Decision rules that save money
- Every dollar of repair prevents a $3–$5 negotiation concession.
- Every dollar of over-improvement returns roughly $0.40–$0.50.
- Match upgrades to neighborhood comps. Don’t spend to create a feature the market won’t pay for.
Bottom line If you want the biggest lift for the least risk before selling, prioritize curb appeal, then targeted kitchen updates (minor remodels), then smart bathroom work (midrange remodels or useful additions). Avoid over-improving beyond your market’s comp ceiling, and fix anything an inspector would flag. For solar, owned systems do add value; leased systems usually don’t.
Sources: Remodeling Magazine / Zonda 2025 Cost vs. Value Report (national averages). For precise ROI in your neighborhood, talk to a local experts to factor in comps, buyer expectations, and market-specific demand. Call me with questions! Karen Daugerdas, Coldwell Banker REALTOR®, PSA®, SRES, SFR®, ABR®, CFSP®, 847.494.1102, karen.daugerdas@cbrealty.com.
Is your home ready for summer storms?
Summer storms can pop up quickly, bringing heavy rain, wind, and even flooding. Here are a few smart steps homeowners can take to protect their property and stay prepared:
- Clear Gutters & Downspouts – Make sure water flows away from your home to prevent leaks and foundation damage.
- Trim Trees & Branches – Cut back any limbs close to your home or power lines that could fall during strong winds.
- Secure Outdoor Items – Tie down or store patio furniture, grills, and decorations so they don’t become projectiles.
- Inspect Your Roof – Replace missing or damaged shingles and check flashing to prevent water from seeping in.
- Seal Windows & Doors – Caulk gaps and use weatherstripping to keep water and wind out.
- Check Your Sump Pump – Test it to make sure it’s working properly and consider a battery backup in case of power outages.
- Prepare an Emergency Kit – Stock flashlights, batteries, bottled water, non-perishable food, and a first-aid kit.
- Review Insurance Coverage – Make sure your homeowner’s policy covers storm-related damage, including flooding if you’re in a high-risk area.
Have a real estate question? Contact Karen Daugerdas, Coldwell Banker REALTOR®, 847-494-1102, karen.daugerdas@cbrealty.com.
Decluttering for Seniors: Creating a Safer, Simpler, and More Peaceful Home
Don’t think that decluttering when you’re in your later years means getting rid of everything. It’s more about making space for what truly matters. The most successful approach centers on three key priorities: improving safety, honoring meaningful memories, and simplifying daily routines. A well-organized home should feel easy to move through and calming to live in, while still reflecting a lifetime of stories and cherished belongings.
These practical, gentle decluttering tips are designed for seniors and their families, focusing on steady progress without pressure.
Begin with Safety
Safety is often the most important place to start. As we age, everyday items around the home can become unexpected hazards. Something as simple as a loose rug, crowded furniture, or a cord across the floor can increase the risk of a fall.
Take a walk through the home together and notice how it feels to move from room to room. Small adjustments can make a big difference:
- Clear hallways and main walking paths
- Rearrange or remove furniture that narrows space
- Secure loose rugs and move cords away from walkways
Once pathways are open, additional safety improvements become more effective. Better lighting improves visibility, grab bars provide support in bathrooms, and handrails add stability on stairs. Non-slip mats can help prevent accidents near tubs and showers.
If there are concerns about balance, vision, or chronic pain, consulting a doctor or occupational therapist can help identify the most important changes.
Keep the Pace Small and Calm
Decluttering doesn’t need to happen all at once. In fact, slower is often better. Large projects can feel overwhelming, while small, focused efforts build confidence and momentum.
Start with just one drawer, shelf, or cabinet. Short sessions—about 30 to 60 minutes—work well, followed by time to rest. Each completed area brings a sense of progress and accomplishment.
It’s helpful to begin with spaces that carry less emotional weight, such as:
- Pantry shelves
- Bathroom cabinets
- Linen closets
- Old mail or expired food
Save more sentimental items, like photos and keepsakes, for later. As confidence grows, those decisions tend to feel easier.
For family members, it’s important to remember that this process can be emotional. Patience and steady progress matter far more than speed.
Use a Simple Sorting Method
Too many choices can quickly become exhausting. A simple system helps keep things manageable. Use four clear categories:
- Keep
- Give to family/friends
- Donate
- Discard
Place labeled boxes nearby so each item has a clear destination. Gentle, supportive questions can guide decisions:
- “How can this room feel easier to move through?”
- “What feels right for this item?”
- “Would you like to keep this or pass it on?”
If something brings up strong emotions, it’s perfectly okay to set it aside and return to it another day.
Focus on High-Impact Areas
Completing one room or zone at a time builds a sense of accomplishment and keeps the process from feeling scattered. Some areas offer especially meaningful improvements:
- Kitchens: Clear out extra dishes and unused tools
- Bathrooms: Simplify cabinets and improve accessibility
- Bedrooms: Reduce clutter for better rest and safety
- Hallways: Ensure clear, open pathways
When it comes to clothing, rarely worn items often become obvious once everything is visible. Keep what fits current routines and comfort.
It’s also best to avoid buying those storage bins too early. Once you “hide” stuff in those, you end up with a sea of bins without actually reducing the clutter. Decluttering first helps reveal what storage is actually needed.
Treat Sentimental Items with Care
Letting go of sentimental belongings can be the hardest part, and that’s completely understandable. These items often hold deep personal meaning and represent important life moments.
Instead of focusing on quantity, consider keeping a smaller collection of truly meaningful pieces. You can also preserve memories in other ways:
- Take photos of special items (my favorite)
- Write down the stories behind them
- Create a memory book
Sharing heirlooms with family members while you can still tell their stories can be especially meaningful. At the same time, it’s important to respect that not every item will hold the same significance for others.
Above all, never remove sentimental items without clear consent. Trust and respect matter more than speed.
Simplify Paper Clutter
Paper clutter tends to build up quietly and can quickly become overwhelming. Start by gathering the most important documents:
- Identification
- Insurance policies
- Wills and legal papers
- Home deeds
- Recent tax returns
Keep originals in one clearly labeled, secure location. If you’re unsure about a document, place it in a “check later” folder instead of making a rushed decision.
Digital copies of key documents can help reduce physical clutter while keeping everything accessible. Meanwhile, old manuals, duplicate papers, and outdated statements can often be safely discarded once essential information is preserved.
Use Storage with Intention
Some belongings may not be needed every day but still hold value. Seasonal decorations, extra furniture, and family keepsakes often fall into this category.
Moving these items out of main living spaces can make the home safer and easier to navigate, while still keeping them within reach when needed. Thoughtful use of storage can support aging in place by reducing clutter without forcing difficult decisions too soon.
Climate-controlled storage is especially helpful for protecting sensitive items like photos, documents, wooden furniture, and electronics from damage caused by temperature changes or humidity.
It’s also worth considering how storage costs fit into long-term plans. Monthly storage expenses can vary widely depending on location, and factoring them into a retirement budget can help ensure that downsizing remains manageable over time.
If you have questions, need organizational resources or want to discuss rightsizing, call Karen Daugerdas, your Coldwell Banker Seniors’ Specialist & real estate broker, 847.494.1102, karen.daugerdas@cbrealty.com.
Buying a home? How hard can it be?
Buying a home can be complicated, but you can make the process easier by following some tips. In Illinois, you need a mortgage pre-approval or Proof of Funds (if you are paying in cash); hiring a real estate attorney to review the contract & conduct the Closing; & getting a good Inspector. These are things I assist with as your Buyer’s agent & REALTOR®. For me, you’ll need to have a signed Buyer’s Agreement so we can begin the process.
House hunting is the fun part. Make a list of your must-haves & the things that are negotiable for you & your family.
Steps to Buying a House
- Get Mortgage Pre-Approval: Secure a lender to understand your budget and show sellers you are serious.
- Conduct your Home Search & Make an Offer: I’ll assist with putting together a competitive offer, as well as negotiate the Closing date & Earnest Money payment & amount.
- Attorney Review & Inspection: Within 5 days of an accepted offer, attorneys begin a review period. Schedule a home inspection to check for issues like radon, which is common in Illinois.
- Finalize Financing & Appraisal: The lender hire an Appraiser to determine the value of the home & finalize your loan. If there are any discrepancies, we’ll negotiate those, too.
- Closing: Review all documents, pay closing costs (typically 2-5% of the purchase price), and receive the deed.
Important Illinois-Specific Considerations
- Attorney State: Attorneys are highly involved in reviewing/modifying contracts, negotiating inspection issues, and managing title work.
- High Property Taxes: Illinois has the highest property taxes in the US; research the tax rates for specific neighborhoods, as they vary widely (e.g., Cook County can exceed 2%).
- Radon Testing: Always include a radon test in your inspection.
- Closing Timeline: Most Illinois transactions close within 30 to 45 days.
Don’t forget that I offer a complimentary Buyer’s Guide to Real Estate! Send your request to karen.daugerdas@cbrealty.com or call 847.494.1102.
Is 2026 the year you decide to sell?
Is 2026 the year you decide to sell? Well, according to predictions, it can be a good decision.
This year is generally projected to be a good year for sellers, characterized by a market rebalancing with increased inventory, slightly lower mortgage rates, rising incomes outpacing price growth, and motivated but careful buyers, leading to healthier sales activity.
The prediction is that we will see a more “balanced” market with less competition than in the last few years. Of course, well-priced, updated homes will still be the quickest, top sellers.
Key factors making 2026 good for sellers:
Increased Inventory & Sales:
More homes coming on the market and boosting sales.
More Affordable Rates
Mortgage rates are lower, improving buyer purchasing power.
Balanced Market:
A more balanced market between buyers and sellers, with more realistic pricing.
Desirable Features will be the top sellers:
Homes with EV chargers, energy efficiency, and modern features will be in higher demand.
Motivated Buyers:
Buyers will be ready to move, though they’ll be more budget-conscious. Pricing your home correctly will be crucial.
Personal Timing Matters:
Life events (job, family) often outweigh market timing; a balanced market offers a good window for many.
If you’re considering selling, call Karen Daugerdas, your local Pricing Advisor & Real Estate Broker, for a current market value of your home. 847.494.1102, karen.daugerdas@cbrealty.com.
New Year Home Checklist: Protect Your Home & Your Peace of Mind
A new year is the perfect time to take stock of your home — not just for interior refreshes, but to protect your investment and simplify your life. A few focused tasks now can save you time, money, and stress down the road. Below are easy-to-follow steps to start the year right, plus tips and templates to help you complete each item.
- Create a Video Inventory (and Back It Up) Why: Photos and lists are useful, but a room-by-room video gives an immediate, date-stamped visual record of your home and belongings. That helps for insurance claims after theft, fire, or natural disasters.
How to do it:
- Take your phone or camera and walk through the house room by room. Narrate what you’re filming (room name, date, and notable items).
- Focus on high-value items (jewelry, electronics, appliances, artwork), serial numbers, make/model tags, and any pre-existing damage or features of the home (flooring, windows, built-ins).
- Don’t forget exterior items: landscaping, shed contents, outdoor furniture, and detached structures.
- Keep videos steady and close enough to capture details when needed.
Storage and backup:
- Save a copy in the cloud (Google Drive, iCloud, Dropbox) and another offline copy (external hard drive or USB).
- Consider emailing a copy to yourself or storing it in a secure file folder so it’s accessible if devices are lost or damaged.
Sample narration/script: “January 5, 2026 — Living room. Sofa (make/model), two end tables, 60-inch TV (serial number…), framed painting over fireplace, no visible damage to mantel…”
- Review and Update Your Home Insurance Why: Life changes — new purchases, renovations, or safety upgrades — can affect how much coverage you need. Being underinsured is costly.
Checklist:
- Make a list of new high-value items purchased in the past year (jewelry, cameras, laptops, musical instruments).
- Note recent renovations (kitchen remodel, roof replacement, finished basement) and safety upgrades (new roof, security system, smoke detectors).
- Compare your calculated replacement cost to your policy’s dwelling coverage and personal property limits.
- Confirm any deductible changes and whether you have adequate liability coverage.
Actions:
- Contact your agent or insurer with updated information and photos/video.
- Ask about discounts for safety upgrades (alarm systems, smoke detectors, deadbolts) and for bundling policies.
- Set a calendar reminder 60 days before your policy renewal to reassess.
- Check Your Home Warranty Why: If you have a home warranty, it may still cover repairs or replacements for appliances and systems. Knowing the coverage and expiration dates helps you plan any eligible work.
Steps:
- Locate your warranty contract and read covered items and exclusions.
- Note warranty expiration/renewal dates.
- Make a list of any repairs you’ve been postponing — appliances, HVAC, water heater — and check if they qualify for coverage.
- If your warranty is nearing expiration, decide whether to renew based on service history and likelihood of future repairs.
- Review Mortgage and Loan Documents Why: Mortgage rates, escrow accounts, and loan terms can change. An annual review keeps you informed and prepared.
What to check:
- Current interest rate, remaining balance, payment schedule, and any escrow changes.
- Any notices from your lender about adjustments or opportunities (refinance, principal reduction).
- Tax documents and closing paperwork in case of disputes.
Storage tip:
- Buy a small fireproof folder or safe and keep originals there. Also create encrypted digital copies stored in the cloud and on an external drive.
- Perform a Home Security Check Why: Security upgrades reduce the risk of burglary and may lower insurance premiums. They also give you peace of mind.
Checklist:
- Evaluate locks on exterior doors and consider deadbolts if you don’t have them.
- Test all smoke and carbon monoxide detectors; replace batteries if necessary.
- Inspect exterior lighting and add motion-sensor lights where helpful.
- Consider a monitored or self-monitored security system or cameras. Many systems are affordable and easy to install.
- Inform your insurer of security additions — you may qualify for discounts.
Bonus: Simple Annual Maintenance Tasks to Combine with These Steps
- Test sump pump, garage door auto-reverse, and GFCI outlets.
- Clean gutters, check roof for damage, and inspect the foundation for cracks.
- Service HVAC and change air filters.
- Flush water heater to remove sediment (or schedule a pro).
Practical Tools and Templates
- Video Inventory Template (quick script):
- Start: “Date — Address — Room name”
- Record: major items, serial numbers, any damage, make/model
- End: “End of inventory for [room].”
- Digital folder structure suggestion:
- /HomeInventory/Video
- /HomeInventory/Photos
- /HomeInventory/Receipts
- /Insurance/Policy
- /Mortgage/Documents
- Reminders:
- Set calendar alerts for insurance renewal (60 days prior), warranty expiry (30 days prior), and annual maintenance (spring/fall).
A little time now means a lot less stress later. Block an hour this weekend to start your video inventory, then spend 15–30 minutes reviewing insurance and warranties. Have questions? Call me. Karen Daugerdas, your Coldwell Banker Real Estate Broker, 847.494.1102.
